Week 2 Interpretation
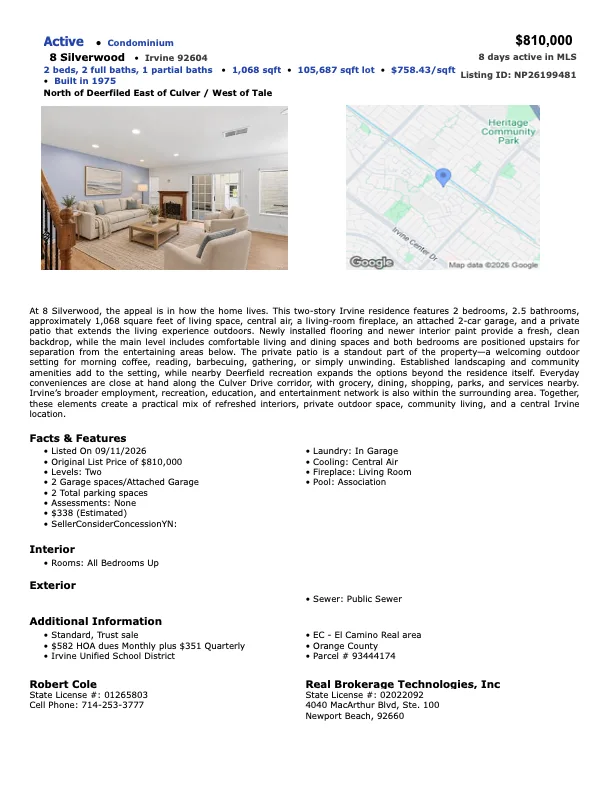
Week 2 gave us a clearer picture of how the market is responding to 8 Silverwood. Marketing exposure remained strong across paid social, the property website, listing portals, agent outreach, and MLS promotion, but that exposure has not yet translated into a corresponding increase in buyer activity.
During the reporting period, the property had one private showing, no new direct inquiries, and no buyer traffic at the October 3 open house. Follow-up was completed after the October 4 showing, but buyer feedback had not yet been received as of the reporting close. At this point, the pattern is not a lack of visibility; it is limited conversion from exposure into active buyer engagement.
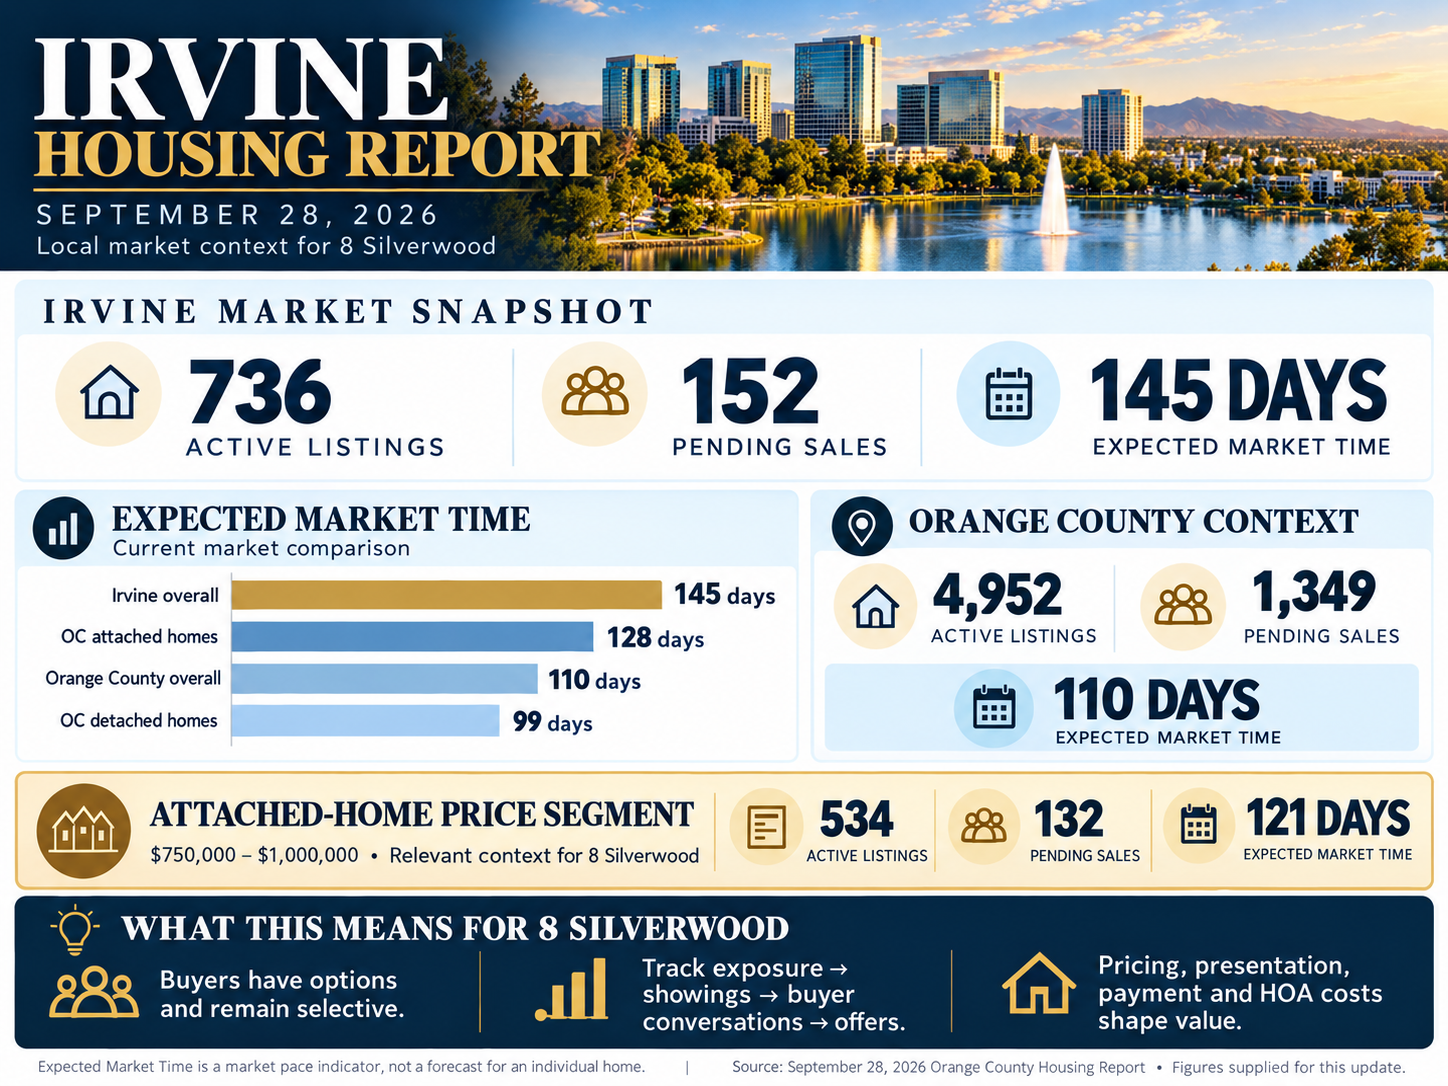
The competitive environment has not changed materially enough to justify a new pricing analysis. 8 Fuchsia and 31 Meadowgrass remain relevant active comparisons, and both have continued accumulating market time. The broader Irvine market has improved somewhat, but the attached-home segment relevant to 8 Silverwood remains slower and more selective than the broader market.
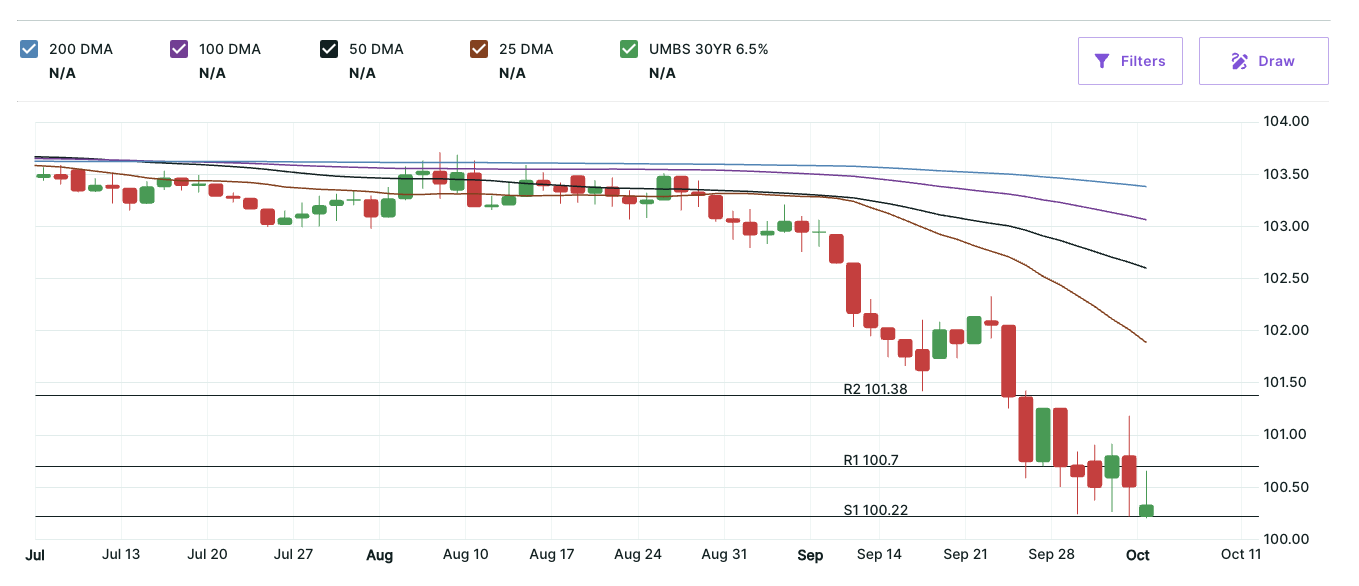
Financing also became somewhat less favorable this week. Mortgage rates moved higher, while mortgage-backed securities weakened again. That does not change the asking price of the property, but it can affect how financed buyers evaluate monthly payment, HOA costs, and overall value relative to competing options.
Based on the first two weeks, I do not think the evidence supports reacting to any single data point. At the same time, we now have enough activity to begin watching the conversion pattern more closely. Week 3 should tell us whether continued exposure begins producing stronger showings and conversations, or whether the property’s positioning needs to be reconsidered.